
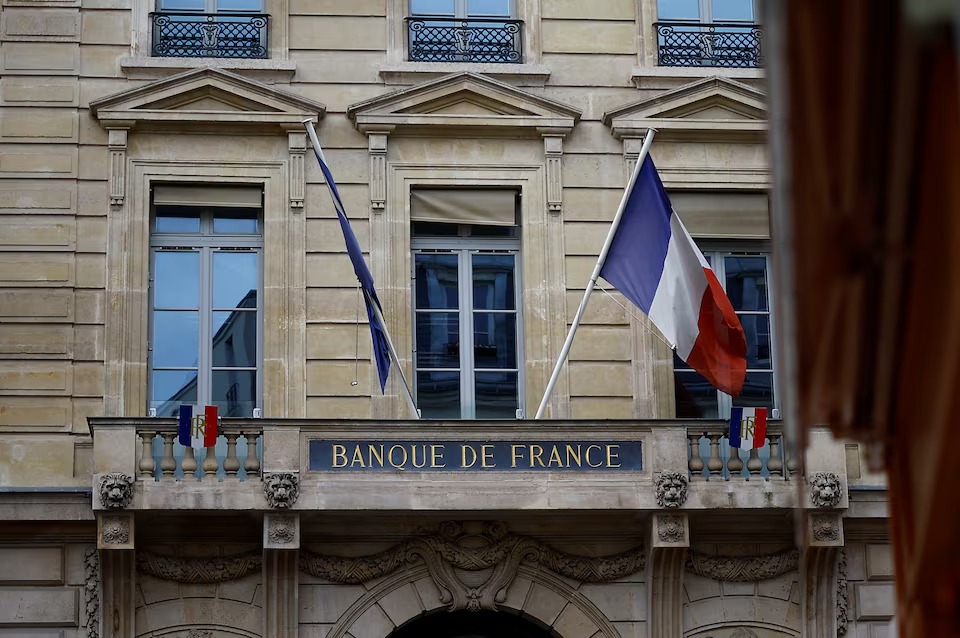
LONDON/PARIS, September 19 – France is facing renewed pressure in financial markets as the premium investors demand to hold its government bonds over German debt has climbed above 100 basis points, reaching levels last seen during the euro zone debt crisis in 2012.
The widening spread reflects growing concern over France’s public finances, the difficulty of reducing its budget deficit and the political uncertainty surrounding next year’s presidential election.
The development is significant because French government debt has traditionally been viewed as one of the euro zone’s major relatively safe assets. The latest move suggests investors are demanding greater compensation for the risks associated with holding French bonds.
WHY HAS THE FRANCE-GERMANY BOND SPREAD RISEN?
The yield on France’s 10-year government bonds has increased more sharply than those of other major developed economies during a broader global bond selloff. Rising energy prices have added to inflation concerns and increased expectations that the European Central Bank could keep interest rates higher for longer.
France’s fiscal position has become a particular source of concern. The government is attempting to bring its budget deficit down from 5.4% of economic output this year to 5% next year, a goal that depends on around €54 billion in spending reductions.
Those measures face opposition from rival political groups, creating the possibility of further political instability and complicating efforts to implement fiscal consolidation.
France is already expected to miss its original 5% deficit target for this year after weaker-than-anticipated economic growth. Higher energy costs linked to the conflict in the Middle East could put additional pressure on economic activity.
Political developments are adding another layer of uncertainty. Marine Le Pen of the far right and Jean-Luc Melenchon of the far left are among the leading figures in the contest for next year’s presidential election. Melenchon’s proposal for the French central bank to cancel government debt held on its balance sheet has unsettled investors, while Le Pen has supported lowering the retirement age for some workers, a policy that could increase pressure on public finances.
France’s bond spread has widened by about 40 basis points since June. Italy has also experienced an increase, although its move has been considerably smaller.
WHAT DOES THE WIDER SPREAD MEAN FOR FRANCE’S FINANCES?
A larger premium on French government debt means the state faces higher borrowing costs. It also increases the expense of servicing existing debt as large volumes of borrowing, including hundreds of billions of euros raised during the COVID-19 pandemic, are refinanced.
Debt-servicing costs have already become France’s largest budget expense. The government estimates that these costs will be €4.5 billion above its earlier projection this year because of higher interest rates. The additional cost is expected to rise by another €10 billion next year.
Economists are concerned about a potential feedback loop. If economic growth remains weak while borrowing costs increase, the amount France needs to spend on interest payments could rise further, making deficit reduction more difficult. Breaking that cycle would require the government to achieve a primary budget surplus, something France remains far from doing.
WHY DOES IT MATTER TO FINANCIAL MARKETS?
The scale of the spread is particularly important because France has one of the largest government bond markets in the euro zone.
The premium on French 10-year debt over German bonds has now reached 104 basis points. The last time the difference moved into three-digit territory was in 2012, when investors were questioning the stability of the euro zone itself.
France is also currently paying a larger premium than Italy, despite Italy carrying a higher debt burden and having lower credit ratings.
Some investors have consequently become more cautious about holding French government bonds.
“France has real problems, and that they’re not going to be solved anytime soon,” said David Zahn, head of European fixed income at Franklin Templeton, referring to the significance of a spread above 100 basis points.
CAN THE SPREAD WIDEN FURTHER?
The sharp rise so far has led some analysts to argue that the scope for another major increase may be limited in the near term. At higher yield levels, investors may eventually decide that the additional return adequately compensates them for taking on French sovereign risk.
Chris Jeffery, head of macro strategy at L&G, said he had recently closed a position betting against French bonds, arguing that investors must eventually decide whether the compensation available is sufficient for the risk involved.
Political developments, however, could trigger another increase in the spread. A government collapse that leaves France without an approved budget could unsettle markets further. Uncertainty could also intensify if Le Pen and Melenchon were to face each other in the second round of the presidential election.
Societe Generale has not ruled out the France-Germany spread reaching 120 basis points, highlighting how closely investors are watching both France’s fiscal plans and its political outlook.